CIS verify subcontractor online: can you trust their word?
Your subcontractor says you should pay without deductions. HMRC's payment instruction decides. If they've worked for you before, your old monthly returns establish whether you need to verify them again.
Your subcontractor says, “I’m registered for gross payment.” HMRC’s verification comes back saying you must deduct.
Your subcontractor cannot decide whether you pay without Construction Industry Scheme (CIS) deductions. HMRC gives that instruction, even if the subcontractor says otherwise. What they tell you is not the basis for the treatment, and their assurance is outside the protection the CIS Regulations give you.
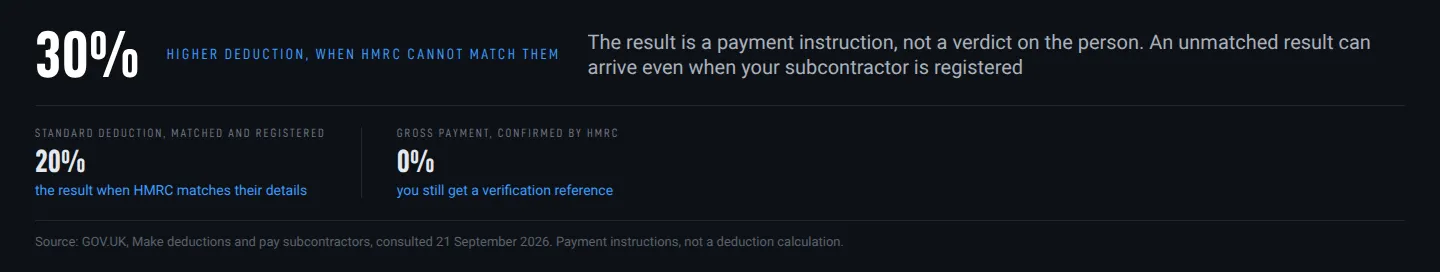
HMRC’s Make deductions and pay subcontractors guide lists standard deduction at 20% and higher deduction at 30%. Gross payment means no CIS deduction, shown as 0%.
Employment status is a separate decision before treating someone as a subcontractor, covered in CIS explained for UK trades. Verification establishes their CIS payment treatment. If you included a returning subcontractor on a monthly return in the current tax year or either of the previous two, you need not verify again.
CIS verify subcontractor online: the registered details must match
You are taking on a new sole trader. Regulation 6(3) of the CIS Regulations requires an agreed contract or formally accepted tender before verification.
Your own CIS contractor registration is separate. You need your business tax account login, with CIS added. GOV.UK’s Sign in to the Construction Industry Scheme (CIS) online service directs you to add CIS through HMRC’s online services page if needed.
Before starting, you need the details listed in CIS340, HMRC’s contractor guide:
- Your name and Unique Taxpayer Reference (UTR), HMRC’s tax reference for you.
- Your accounts office reference, identifying your HMRC accounts office.
- Your employer reference, identifying your employer scheme.
- The sole trader’s registered name and UTR, plus their National Insurance number.
Your contractor registration letter supplies information needed to operate CIS, including your employer reference.
Your subcontractor’s details must exactly match their HMRC registration, as GOV.UK requires. You confirm the contract or accepted tender and submit. HMRC returns the payment instruction and verification reference.
HMRC’s manual CISR12150 requires online verification for ordinary checks, through HMRC’s free CIS online service or recognised commercial CIS software. GOV.UK requires commercial software for more than 50 subcontractors.
The exception sits on HMRC’s Service availability and issues page, which keeps telephone verification available when the online route fails. It covers specific cases: missing telephone-verification records and some partnership matching failures. An operator can provide telephone verification where required, with a limit of 10 subcontractors per call.
For those exceptions, HMRC’s CIS: general enquiries contact page gives the helpline number as 0300 200 3210.
Issue 1 of the service-issues page requires every telephone verification to be repeated online afterwards so the online record is updated. The telephone result does not update it automatically. Your ordinary sole-trader verification still goes online from the start.
HMRC leaves response timing unspecified in Verify subcontractors and CIS340. You can start once the contract is agreed; verification must be completed before payment. An assumed instant response is no basis for scheduling payment.
A matched result still needs a payment instruction
With a matched result, HMRC has found your subcontractor’s CIS record. You still receive an instruction for payment under deduction or gross payment.
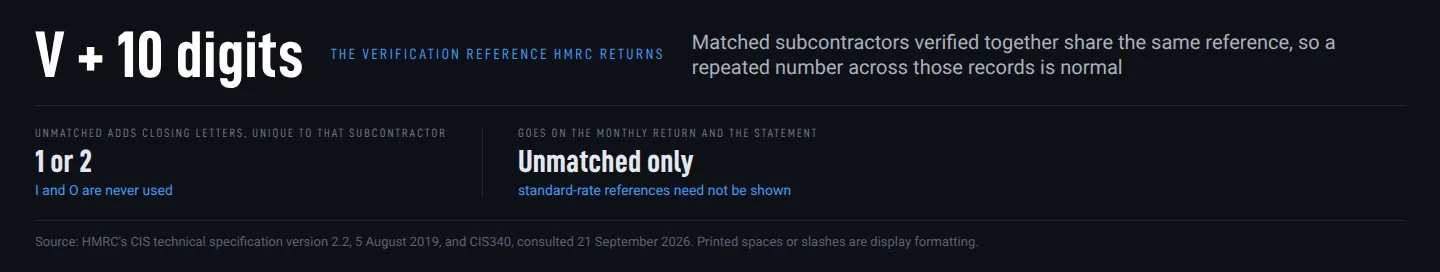
CIS340 requires you to record every verification reference. All matched subcontractors verified together share it. A repeated number across those records is normal.
Only the complete reference for a 30% deduction must also appear on your monthly return and the payment and deduction statement you give the subcontractor. Standard-rate and gross payments do not require it on either document.
For a limited company, you use the company UTR
If a limited company invoices you, its details go into verification.
CIS340 requires the company’s name and UTR, together with its company registration number. HMRC’s manual CISR51040 specifies the Corporation Tax UTR. The director’s personal UTR identifies a different taxpayer.
When a sole trader incorporates, CIS340 says the old registration cannot be used for the new business. The new business needs its own CIS registration, with gross status required before it can receive gross payments. You supply the new company’s identifiers.
The business category matters too. HMRC’s Service availability and issues page says a wrong category can prevent verification. Its remedy is to delete the subcontractor record and recreate it correctly.
Partnership verification needs identifiers for both business and partner
If you pay a partner on behalf of a partnership, HMRC needs details for both.
CIS340 requires the partnership’s name and UTR. You also supply the partner’s name. For an individual partner, you give either their personal UTR or National Insurance number. For a company partner, you give either its UTR or company registration number.
The partnership UTR and an individual partner’s UTR identify different taxpayers. They are not interchangeable.
CISR51030 requires each partner receiving payments on the partnership’s behalf to register and be separately verified by each contractor. Other partners outside those payments need neither registration nor verification for that role.
Unmatched means 30%. Correct details can change the result
An unmatched result means HMRC could not find a CIS record using the details supplied. It can happen even when your subcontractor is registered. CISR51060 lists incomplete or misquoted details alongside missing or unfinished CIS registration as possible causes.
“Unknown match” can appear when you first add someone to the online list, before verification is complete. HMRC’s service-issues page permits you to amend the information or continue verification. You must finish the process to obtain a matched or unmatched reference.
For a completed unmatched verification, the higher deduction applies. CISR51060 says you pass the unmatched reference to the subcontractor, who checks their details or contacts HMRC about identification and registration.
For a simple data mistake, the manual allows another verification before payment. After correcting the entry, you still need HMRC’s successful match and current payment instruction before changing the treatment.
The verification number matters beyond your own records. CIS340 says unmatched references carry one or two letters unique to that subcontractor, and requires the complete unmatched reference on your monthly return and on the payment and deduction statement supplied after payment. HMRC’s specification gives the format as V plus 10 digits and any closing letters, without printed spaces or slashes when entered electronically.
After registration, HMRC notifies affected contractors of changed status. CISR51060 warns that HMRC does not automatically carry earlier payments and deductions onto the new record. The subcontractor uses the unmatched reference with HMRC to identify that earlier higher-rate period.
Gross payment status comes from HMRC’s confirmation
If your subcontractor expects gross payment and disputes a deduction instruction, you still follow HMRC’s result.
Regulation 6 requires verification with HMRC. Under paragraph 6(7), you may assume someone HMRC verified or notified as registered for gross payment or payment under deduction remains so registered. That entitlement rests on HMRC’s confirmation.
When HMRC confirms gross payment, you pay without CIS deductions. You still receive a verification reference, which CIS340 says you need not show on the monthly return or payment statement.
Either party can request an HMRC ruling on a disputed deduction under CIS340. While the dispute remains unresolved, you must make the appropriate deduction and pay it to HMRC.
Deductions remain due if you fail to verify
Two different things happen, and it helps to keep them apart.
First, you face no standalone penalty just for failing to verify under the CIS Regulations. The deduction is still due: you remain liable for deductions that should have been made, and HMRC can determine that liability against you under regulation 13.
Second, and separately, CIS340 warns of penalties for omitted or incorrect verification declarations on the monthly return, called CIS300. The declaration must accurately state whether you complied with the verification requirements.
Returning subcontractors: the return determines how long the exemption lasts
When someone comes back after a gap, your old monthly returns establish whether another verification is needed.
Within the getting paid paperwork you keep, those returns supply the evidence. CIS340 says you need not verify “if they last included that subcontractor on a return in the current or 2 previous tax years”.
The test uses tax years and inclusion on a return, rather than elapsed time since verification. The tax year runs from 6 April to 5 April. Applying CIS340’s rule to a payment between 6 April 2026 and 5 April 2027, a return from 6 April 2024 onwards counts. If your subcontractor appeared on one of those returns, you need not verify again. If not, you must verify before paying. Someone who worked for you two years ago may or may not be covered, and the date they worked does not settle it.
Where the exception applies, CIS340 requires the same payment treatment as last time, unless HMRC has told you otherwise. A change-of-status notice updates that treatment from its effective date. HMRC’s manual CISR51050 also says a change-of-status notice does not itself require another verification.
The last return containing that subcontractor controls the usual exemption, so you need not verify a subcontractor online again while it holds. HMRC publishes no expiry date for the verification number itself. Once that return falls outside the current or previous two tax years, you must verify again before paying.
Trade resources for tradespeople, straight to your inbox.
Occasionally we will send you a newsletter. Free, unsubscribe in one click.
Keep reading
CIS monthly return deadline: paid on time, but filed late?
Paying HMRC on time can still leave your return late. An empty month also needs reporting unless an exemption applies. Once a return is overdue, its penalty clock keeps running even as the next month comes round.
CIS deduction statement template: what goes in every box
The reference at the top is yours. The UTR is theirs. The statement needs to show what you paid and withheld, with the optional boxes kept separate from the required details.
CIS explained for UK trades
Paying subcontractors puts the CIS deduction, return and paper trail on your business. That applies to your subcontractor payments even on a job in someone's kitchen, and even when another contractor is making deductions from your own invoices.